The SGX Quiet Period: What PR Teams Can and Cannot Say
Ask an investor relations manager at a Singapore-listed company what happens to the inbox a month before results day, and the answer is almost always the same: the phone stops ringing, deliberately, because it has to.
The practice is commonly called an SGX quiet period, and most SGX-listed issuers observe one in some form before they announce their half year or full year results. Few communications teams outside investor relations fully understand where the restriction actually comes from, what it covers beyond director dealings, and how far a company can go in managing media or analyst questions without crossing into selective disclosure. For press and communications teams supporting an SGX-listed client or employer, getting this window wrong carries real reputational and regulatory risk.
What the SGX Quiet Period Actually Covers
The term quiet period does not appear as such in the SGX Mainboard Rules. What exists instead is a dealing restriction: issuers are required, under the Listing Rules’ Best Practices Guide on dealing in securities, to adopt an internal code barring directors and key officers from trading in the company’s shares during a defined window before results are released, typically starting one month before half year and full year announcements and lasting until the announcement itself is made. The restriction exists so insiders cannot profit from information the rest of the market does not yet have.
Running alongside that dealing restriction is a separate, broader obligation: the continuous disclosure rules that require an issuer to announce, promptly and through SGXNet, any information that could materially affect its share price or create a false market. Those obligations do not switch off during the pre-results window. If anything, they become more sensitive, because a casual comment to a journalist or analyst in the weeks before results can itself amount to a selective disclosure of material, non-public information, which is the behaviour the dealing restriction and the disclosure rules are both designed to prevent. Our earlier guide to writing SGX disclosure announcements covers how to structure that SGXNet release itself; this piece focuses on the quieter weeks before it.
Why Communications Teams Get Caught Out
Confusion usually comes from treating the dealing restriction as the whole picture. It technically applies only to directors and officers buying or selling shares, not to what a spokesperson tells a reporter. In practice, though, many Singapore-listed companies extend the same logic to all public comment on financial performance and outlook, closing that broader communications window at the same time the dealing restriction opens. City Developments Limited‘s published investor relations policy is a clear public example: during its closed period, the company states plainly that it does not comment on industry outlook or on the group’s business performance, declining those conversations until results are formally released.
What PR Teams Can Still Say
A quiet period is not a communications blackout in the broadest sense. A company can still issue a press release during the window, provided the content has nothing to do with financial performance or outlook. A product launch, a new regional office opening, a sustainability certification or a community partnership can all be announced as planned, since none of those is the kind of information the restriction is trying to contain.
What changes is how spokespeople respond to anything adjacent to numbers. A polite, pre-agreed holding line, something like noting that the company is in its results preparation period and cannot comment further until the announcement, does more to protect the organisation than an improvised answer that half-addresses the question. Journalists covering SGX-listed companies are generally familiar with this convention and tend not to push hard against it, provided the same line is used consistently rather than offered to one outlet and withheld from another.
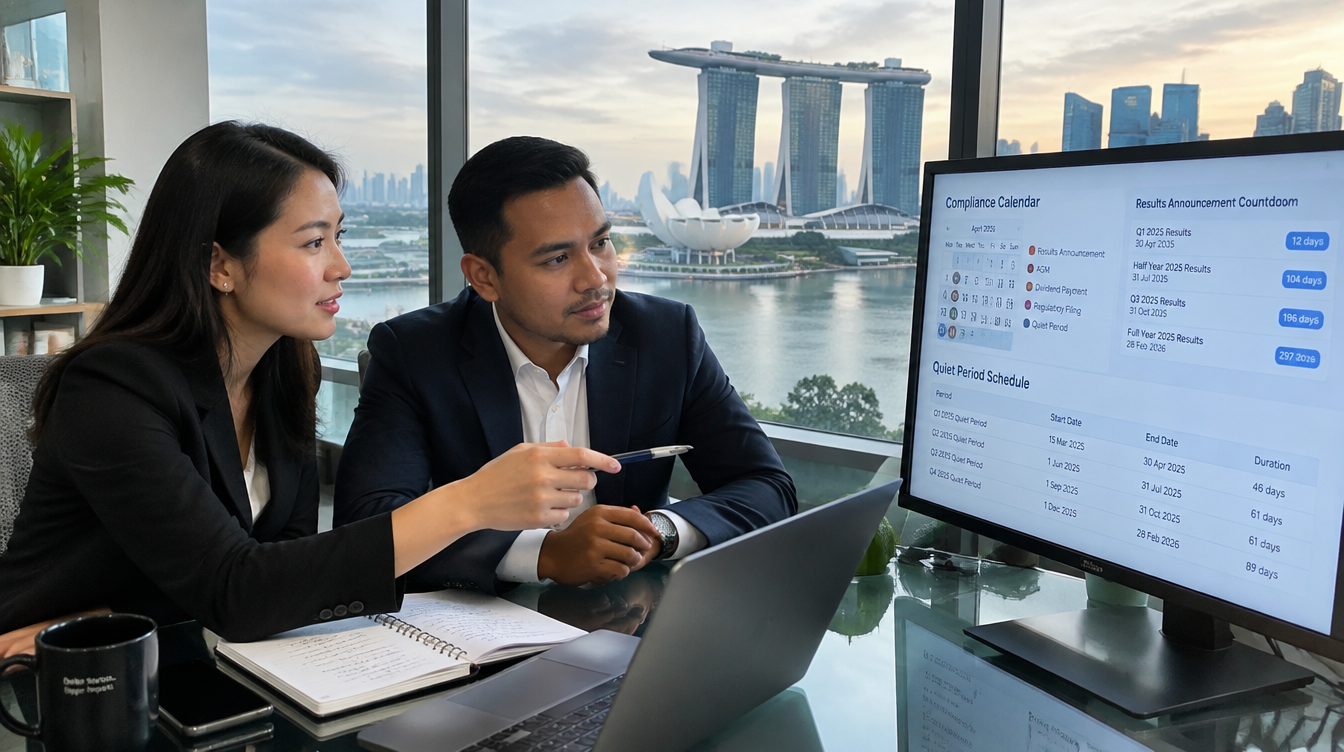
Internally, the best protection is early coordination. A communications team that knows the results calendar a quarter out can brief spokespeople, draft holding statements, and flag announcements that might wander close to performance commentary before the window opens. Leaving that coordination until a journalist calls is where most avoidable missteps happen.
A Quiet-Period Checklist Worth Keeping
Treating the window as a fixed date on the compliance calendar, not a vague instruction to go quiet, is what separates a smooth results season from an awkward one. A short checklist, built once and reused every reporting cycle, tends to cover most of what comes up:
- Confirm the exact start and end date of the restricted period with the company secretary or legal counsel, since it can vary slightly by issuer policy.
- Draft and circulate a single holding statement for media and analyst enquiries before the window opens.
- Flag any non-financial announcements already scheduled for the period so they can be checked against the policy.
- Brief every spokesperson, not only the chief executive or chief financial officer, on what they may and may not say.
- Keep a record of every enquiry received and how it was answered, in case the company is later asked to account for its handling of the period.
- Agree in advance who has the authority to approve an exception if a genuinely unrelated announcement needs to go out.
When Material News Breaks Anyway
Markets do not pause for a company’s internal calendar, and a quiet period does not suspend the continuous disclosure obligations. If something materially price-sensitive happens, an unexpected contract loss, a regulatory investigation, a senior leadership departure, it still has to be disclosed promptly, generally alongside a trading halt request, regardless of where the company sits in its results cycle.
This is where PR teams need the clearest line to legal and investor relations, because a quiet period is sometimes misread internally as permission to delay bad news. SGX RegCo has disciplined companies over the years for sitting on information too long, arguably the more damaging risk. A well-run quiet period protects a company from accusations of selective disclosure, and it is never a reason to withhold something the market is entitled to know. As with any SGX compliance question, this is general guidance only, not legal advice, and a company’s own compliance or legal advisers should confirm how the rules apply to its specific circumstances.
None of this requires an SGX-listed company to treat every reporting season as a crisis. What it requires is knowing, well before the window opens, where the dealing restriction ends and the broader disclosure obligation continues, and building a routine around that distinction instead of reacting to it one phone call at a time. If your team wants a second pair of eyes on a results-season announcement, or steadier support through the weeks around a sensitive reporting window, feel free to get in touch.